

By Jason Dunaway | Your Local Western Tidewater Real Estate Professional
Buying your first home can feel a whole lot closer when you understand the programs that are available to help.
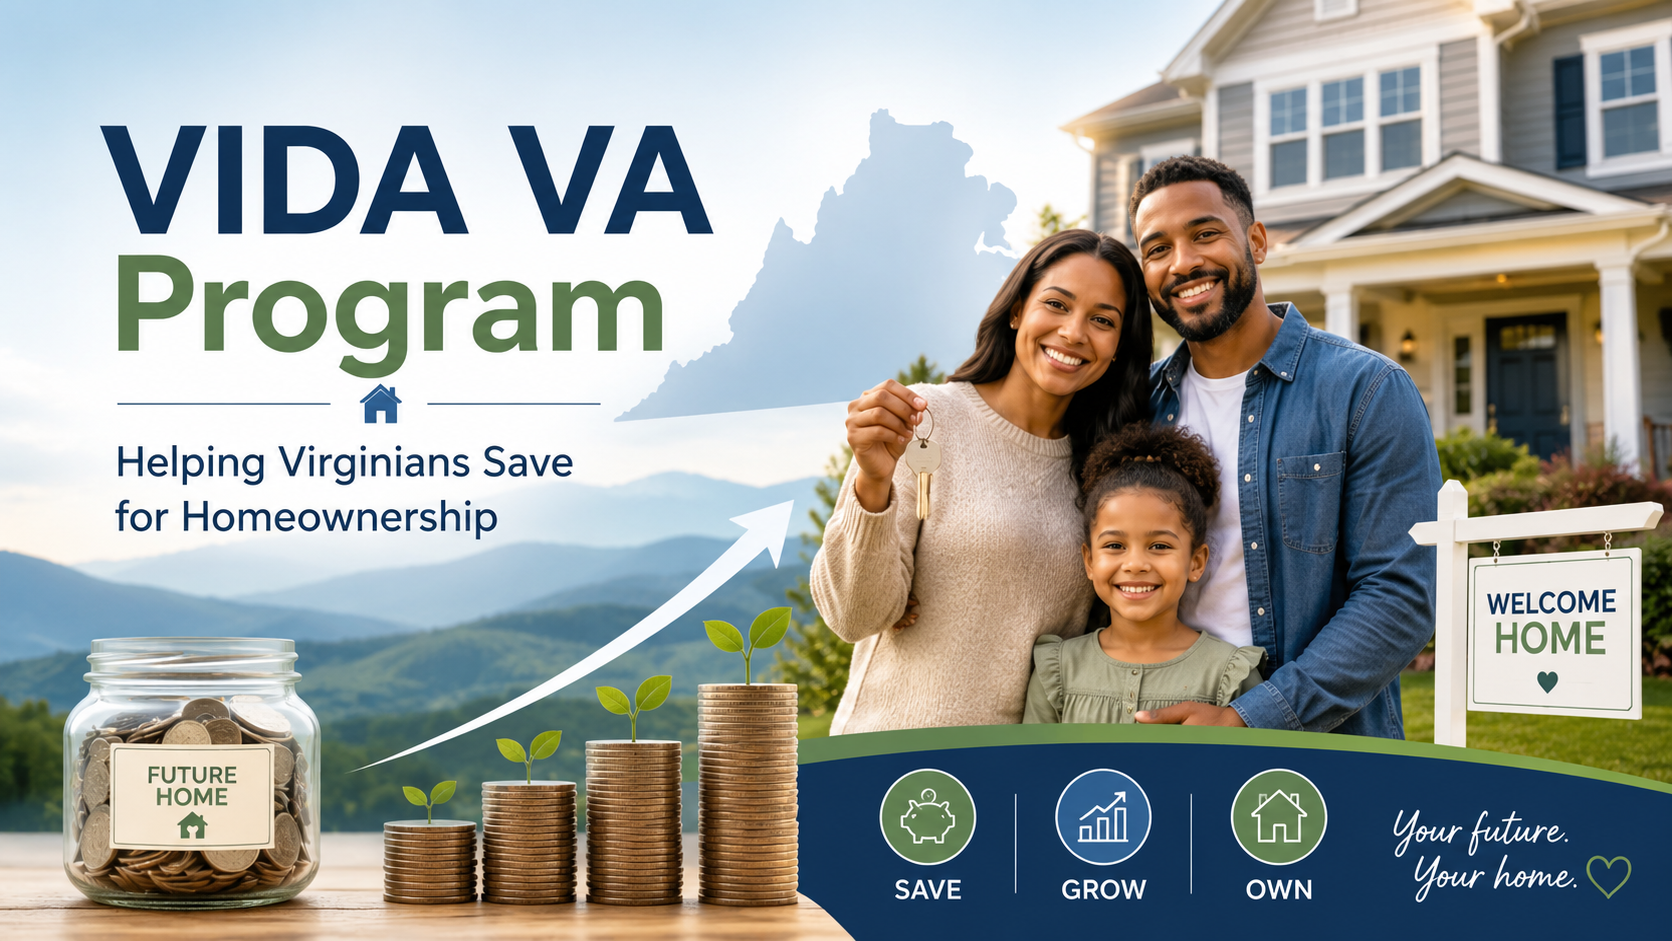
One program I think more buyers in Franklin, Southampton County, Isle of Wight, Suffolk, Smithfield, Windsor and Western Tidewater should know about is VIDA — the Virginia Individual Development Accounts program.
Here’s the part that gets people’s attention:
Save $1,000 and, if you qualify and successfully complete the program, VIDA can provide up to $10,000 in matching funds.
That could mean $11,000 toward your home purchase between your savings and the match.
And no, that’s not a typo.
According to the Virginia Department of Housing and Community Development, VIDA currently matches eligible savings at $10 for every $1 saved, up to $10,000 in matching funds, which can be used toward down payment and closing costs.
So, What Exactly Is VIDA?
VIDA stands for Virginia Individual Development Accounts.
It’s a financial education and matched-savings program administered by the Virginia Department of Housing and Community Development (DHCD) and funded by Virginia Housing. The goal is not simply to hand somebody money and send them house shopping.
VIDA is designed to help eligible buyers prepare financially for homeownership.
Participants work with an approved VIDA intermediary, receive financial counseling and homebuyer education, establish a savings plan, and work toward becoming mortgage-ready.
That education piece matters.
One of the biggest misconceptions I hear is:
“Jason, I make enough money to pay rent, so why can’t I buy a house?”
Sometimes you can.
The obstacle may be the down payment. It may be closing costs. It may be credit. It may simply be that nobody has ever sat down with you and helped you put all the pieces together.
That’s where a program like VIDA can be powerful.
How Does the $10-to-$1 VIDA Match Work?
This is the fun part.
For every eligible $1 you save, VIDA can match it with $10, up to the program maximum.
So, in simple terms:
| You Save | VIDA Match | Potential Total |
|---|---|---|
| $100 | $1,000 | $1,100 |
| $250 | $2,500 | $2,750 |
| $500 | $5,000 | $5,500 |
| $1,000 | $10,000 | $11,000 |
The current VIDA homeownership flyer specifically promotes “Save $1,000 and earn $10,000” toward a first home purchase.
Think about that for a minute.
For somebody who has been saying:
“I could probably afford the monthly payment, Jason. I just don't have enough saved to get started.”
VIDA could completely change that conversation.
Who May Qualify for VIDA?
VIDA isn't available to everyone, and participating does not automatically mean you'll qualify for a mortgage.
DHCD currently lists several basic eligibility requirements. Applicants generally must be:
- At least 18 years old
- A Virginia resident
- A U.S. citizen or legal resident
- Receiving earned income from employment or self-employment
- Within the applicable household income limits
- Within the program's household net-worth limits
- Able to complete the program within approximately 4 to 24 months
The current VIDA candidate materials also address mortgage readiness, including credit, debt and other financial factors. Program participation and funding are subject to eligibility, readiness, available funds and having an approved intermediary serving your locality.
In other words:
Don't disqualify yourself before you talk to somebody who understands the program.
I see people do that all the time.
“My credit probably isn't good enough.”
“I probably make too much.”
“I don't have enough money saved.”
“I've got some debt.”
Okay.
Let's find out what the actual numbers say instead of guessing.
What About Income Limits in Franklin and Western Tidewater?
VIDA income limits vary by location and household size.
The current income-limit document published on DHCD's VIDA page is labeled FY2025. For the Southampton County–Franklin City HUD Nonmetro FMR Area, it lists the following maximum household incomes:
| Household Size | Income Limit |
|---|---|
| 1 person | $52,500 |
| 2 people | $60,000 |
| 3 people | $67,500 |
| 4 people | $75,000 |
| 5 people | $81,000 |
| 6 people | $87,000 |
| 7 people | $93,000 |
| 8 people | $99,000 |
Important: Income limits and program rules can change. Don't use this table as your final eligibility determination. Your VIDA intermediary should verify the current limits when you apply.
Does VIDA Work in Western Tidewater?
There are VIDA intermediaries serving portions of our area.
DHCD's current published intermediary list includes Virginia Housing and Community Development Corporation for areas including Isle of Wight County, Franklin, Smithfield and Windsor. It also lists Norfolk Redevelopment and Housing Authority's HomeNet Homeownership Center as serving Suffolk, among several other Hampton Roads cities.
For Southampton County, I recommend verifying current availability directly with DHCD. The intermediary list currently posted by DHCD is dated April 2024 and does not specifically name Southampton County, even though the VIDA income guidelines include the Southampton County–Franklin City area.
That is another reason I don't like simply handing somebody a link and saying, “Good luck!”
Programs change. Funding changes. Income limits change. Intermediaries change.
Your home-buying plan needs to connect all of those pieces.
Can VIDA Be Combined With Other Homebuyer Assistance?
Potentially, yes — and this is where things can get really interesting.
DHCD says VIDA has often been used alongside other housing programs, including Down Payment Assistance programs, and VIDA is funded by Virginia Housing, which also offers homebuyer lending programs.
Whether programs can be combined in your specific transaction depends on the loan, property, income, program guidelines and available funding.
That means our job isn't simply to ask:
“Can you get approved for a mortgage?”
A better question is:
“What combination of financing and assistance programs gives you the strongest path to sustainable homeownership?”
That's a much better conversation.
Here's How I Would Start
If you're thinking about buying a home in Western Tidewater, don't make looking at houses Step One.
Make building the plan Step One.
We can figure out:
What can you realistically afford?
What does your credit picture look like?
Could VIDA apply?
Are there other Virginia Housing programs worth exploring?
What will you need for closing?
What homes in Franklin and Western Tidewater actually fit that budget?
Once we know those answers, then house hunting gets a whole lot more fun.
Because now we're not just scrolling through pictures online.
We're shopping with a plan.
“But Jason, I'm Not Ready to Buy Yet.”
Perfect.
VIDA is actually a program you should learn about before you're ready to make an offer.
The program is built around saving, education and preparation, and DHCD says eligible savers should be able to complete the process within roughly 4 to 24 months.
So if you're thinking:
“Maybe sometime next year…”
That's exactly why we should talk now.
Waiting until you find the perfect house to figure out financing, credit, assistance programs and closing costs is doing everything backward.
Ready to Find Out If Homeownership Is Possible?
You don't have to know all the terminology.
You don't need to know which loan you need.
And you definitely don't need to have everything figured out before you call me.
That's what I'm here for.
I'm Jason Dunaway, your hyper-local Real Estate Professional serving Franklin and Western Tidewater, Virginia.
My job isn't just opening doors.
It's helping you understand how to get to the door in the first place.
If VIDA, Virginia Housing or another homebuyer program could help you make the move from renting to owning, let's find out.
🏡 Ready to Build Your Home-Buying Game Plan?
Contact Jason Dunaway
WesternTidewaterHomes.com
Tell me:
“Jason, I want to know if I qualify for VIDA.”
We'll start there.
Program availability, eligibility requirements, income limits, funding and lending guidelines are subject to change. VIDA eligibility is determined by the appropriate program administrator/intermediary, not by a real estate licensee. Mortgage qualification is determined by the lender.
Check out this article next